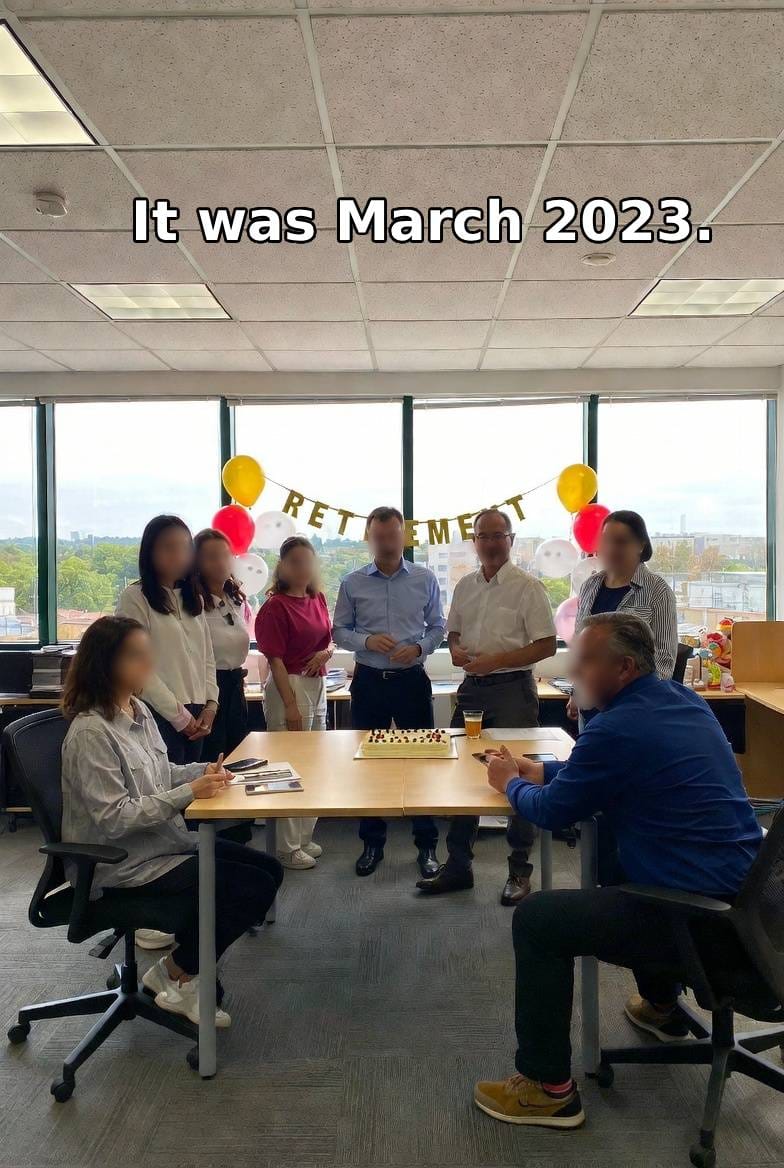
A man I worked with for 10 years retired 8 years later than he had planned.
He was not lazy.
He was not reckless.
He had contributed to his 401k for 35 years
paid off his house, listened to his advisor, and done every single thing the American retirement system had told him to do.
And at his retirement party...
63 years old, eating a piece of supermarket cake, he leaned over to me and said:
"I did everything right, Tom. I just did it wrong. And nobody told me."
That sentence is the reason I wrote this book.
I nodded. I smiled. I said the things you say at a retirement party.
But I went home that evening and I could not let it go.
Because this man was not careless.
He was not reckless.
He was a steady, disciplined, middle-class American
...who had done exactly what the system had asked him to do for 40 years.
He had contributed to the 401k.
He had paid off the house.
He had listened to his advisor.
And he was retiring 8 years later than he had hoped to.
That night I opened a spreadsheet, and for the first time in my adult life:
I asked myself a question I had been avoiding.
What if he is not the exception? What if he is the rule?
So I started looking.
Not at blogs. Not at influencer threads.
I started pulling the boring stuff.
The actuarial reports. The Social Security Administration bulletins.
The Wharton studies.
The things almost nobody reads because they are dense, unflashy, and written by people who would rather calculate than entertain.
And within two weeks, I found the number that made me go quiet at my desk.
In 1991, the average American retired at 57. Today the average American retires at 61.
Four years. In one generation.
If that sounds like a small slip to you...
let me put it the way I had to put it to myself that night.
The average American man lives to about 76.
If your planned freedom starts at 57 and ends at 76, you have 19 years.
If your freedom gets pushed to 61, you have 15.
That is not "4 years lost."
That is 21% of your entire retirement freedom, quietly erased by a system almost nobody was paying attention to.
And here is the part that got me:
It was not happening to irresponsible people.
It was happening to the most disciplined, hardest working, most well-intentioned cohort of savers America has produced in half a century.
In 1995, the average worker said they planned to retire at 60.
Today, that same worker expects 66.
1 in 4 Americans over 50 now says they expect to never retire.
58% of retirees leave the workforce earlier than they planned, but not the way they imagined.
Not in triumph. In layoffs, illness, restructurings they did not choose.
57% of older Americans told Wharton researchers:
with the clarity that only comes at 70 years old, that their biggest regret was not saving earlier.
40% regretted not preparing for healthcare and long-term care costs.
These were not people who blew it on Lamborghinis and poker.
These were school teachers and plumbers and middle managers and nurses. People who trusted the script.
And the script had been quietly rewritten underneath them without anyone sending them the memo.
Pensions got swapped for 401k.
Social Security's full retirement age crept from 65 to 67.
Healthcare costs exploded faster than wages.
Saving rates dropped from 11% in the 1970s to almost 1% by 2005.
Life expectancy pushed past 80.
The "4% rule" that was designed for 30-year retirements started looking shakier for anyone planning 40.
Every single one of those shifts was published.
Every single one was studied, peer-reviewed, documented by the Social Security Administration or the Bureau of Economic Analysis or the Employee Benefit Research Institute.
And almost none of it reached the people who needed it.
My former colleague retired 8 years late because the rules had changed and nobody at his bank, his HR department, or his advisory firm had sat him down and walked him through what those changes actually meant for the date on his calendar.